
It’s more important than ever to link your local government budget to your strategy.
- Code only the discretionary 20 to 30% to strategic goals. Debt service, personnel and mandated services are fixed; alignment matters where new initiatives compete for funding.
- Require every department budget request to link to a citywide goal. Attach revenue estimates, expenditure lists and performance measures so council can weigh the request.
- Use priority-based budgeting instead of base budgeting. Base budgeting keeps funding previously funded items, which makes it hard to drive change.
- Link the budget to a small set of measures someone actually updates. ClearPoint shows which local-government owners haven't updated yet, so teams can follow up before the review.
- Plan the cycle with the linking budget to strategy whitepaper. Fort Collins funds only what links back to its strategic plan through Budgeting for Outcomes.
A local government budget links to strategy when every discretionary dollar is coded to a goal in the strategic plan, and the same scorecard is used to report on both. In practice that means a nine-step annual cycle: roughly six months of preparation, one to two months of approval, then continuous implementation and evaluation against the plan.
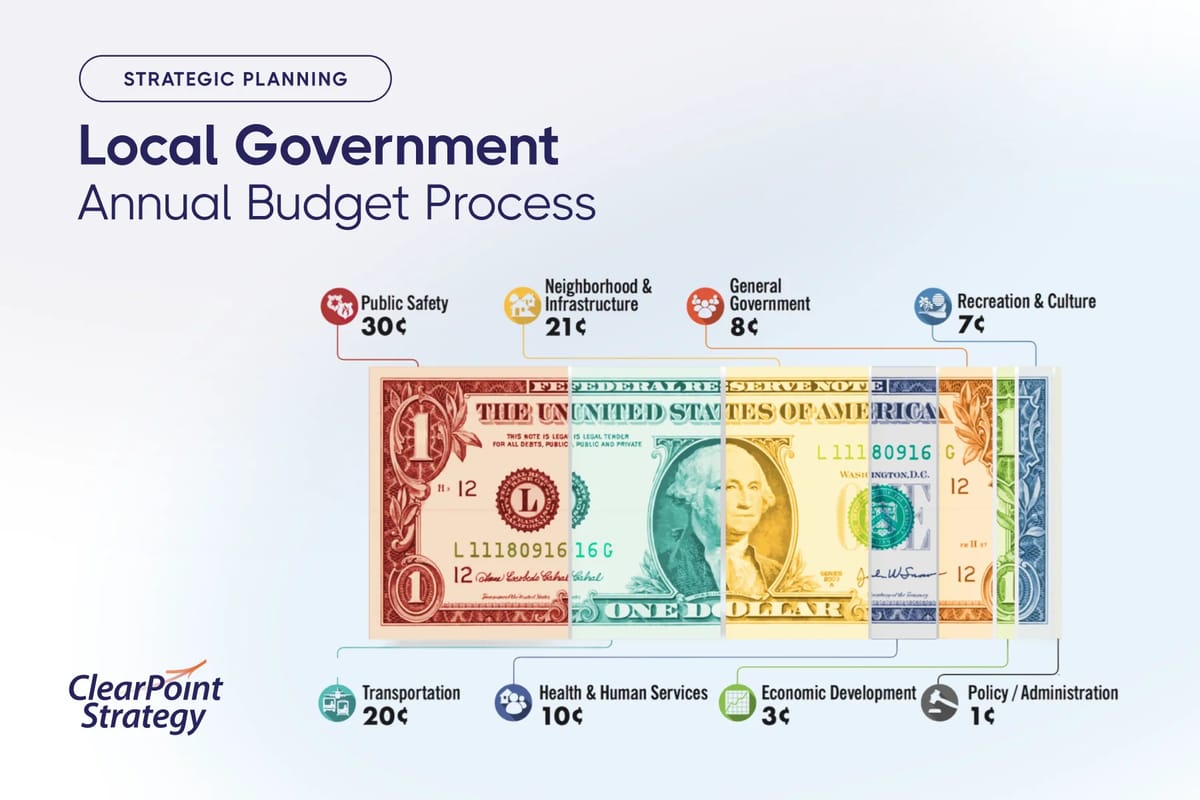
You do not need to code the whole budget. Most of a local government budget is fixed: debt service, personnel, mandated services. The alignment work belongs to the discretionary 20–30%, where new initiatives compete for funding. That is where priority-based budgeting beats base budgeting, and where a linked scorecard changes which projects survive the council session.
Technically, a budget is a spending plan that forecasts revenue and expenses for a local government over a set future period. In practice it does more.
Good financial management is key to realizing a community’s vision, and the budget is one of the main tools for getting there. It keeps local leaders financially accountable, and it sets out plans for the future of the community.
With such a big job to do, it’s no wonder that the local government budget process is usually long and laborious. We don’t think it has to be. This guide explains an approach to budgeting grounded in strategy, which we believe delivers the best results. At the end, you can read how one city has used this approach to make its community a great place to live, work, and play.
Why A Local Government Budget Should Be Tied To Strategy
At its most basic, creating an annual budget means planning for expected income and spending in the upcoming fiscal year. That means allocating money across departments to finance operations and provide public services.
These needs often call for two different types of budgets:
- One is an operating budget, which is exactly what it sounds like. It lists expenditures necessary for day-to-day operations.
- The second is a capital budget, which includes financial plans for long-term capital improvements, facilities, and equipment. Both types of budgets play an important role in quality of life for residents.
For example, a city might need to budget annually for snow removal; it might also invest in a longer-term streetscape project that includes installing new and replacement sidewalks throughout the city.
Local governments that use both capital and operating budgets then consolidate them to indicate the amount of total estimated revenues available for the current period and the amount of new debt to be incurred for projects in the capital budget (which usually won’t generate revenue right away).
In general, governments can estimate operating expenses well from year to year because they are largely fixed costs. Most of the negotiating happens around the capital budget: which projects you will take on in the near future, and what their impact on the community will be.
To maximize your budget, it’s wise to choose projects that reflect your government’s stated future priorities, which you have outlined in your strategy and (presumably) communicated to your constituents.
Funding the projects that line up with your vision helps you achieve those long-term priorities. It also promotes accountability and shows good fiscal management. Your strategy also serves as a bridge between different departments, helping steer everyone toward common goals.
See how other local governments have successfully connected budget to strategy:
Learn how to link budget to strategy in our whitepaper
What the numbers look like in other local governments
Before you redesign the process, it helps to know the scale other cities and counties are actually operating at. These are live figures from the 161 local government organizations running strategy on ClearPoint:
Local government benchmarks — ClearPoint platform, August 2026
161 local government organizations tracked
398 KPIs — median per organization
146 initiatives — median per organization
19 plans — median per organization
2.5× the completion rate when an initiative has a named owner (21.5% vs. 8.7%)
The last line is the one that decides whether budget-to-strategy linking survives past year one. A median local government is carrying 398 KPIs across 19 plans. If the people named against those measures never touch them, the budget conversation reverts to last year’s numbers plus an increment. That is the base-budgeting trap described above. Link the discretionary 20–30% of the budget to a smaller set of measures that someone actually reports on, rather than coding every line against the whole plan.
9 Steps For Conducting An Annual Budget Process That Links To Strategy
Here are the steps in the local government budget process, with a focus on how to link budget to strategy along the way. Note that this process could take up to eight months, so it begins well in advance of a new fiscal year.
Phase 1: Preparation (Takes Up To 6 Months)
1. Identify strategic objectives and gather department operating budget requests
Before a budget can be drafted, city managers need input from each department; that input comes in the form of budget requests. But before departments can submit their requests, they must be fully aware of the city’s strategic objectives, and identify related strategic objectives of their own, based on how their activities will best support the city’s strategic priorities. Every budget request should link in some way to city-wide goals.
To formulate individual budget requests, department directors may gather input from their program managers. Each request should come with context that will help during deliberation, for example revenue estimates, detailed expenditure lists, or program performance measures.
2. The chief executive holds meetings with department directors to review requests
Once department directors submit their budget requests, the chief executive begins the review process, holding meetings with department directors and budget staff to review the requests.
These discussions are usually held in the context of one of four types of budgeting approaches: priority-based budgeting, zero-based budgeting, budgeting for outcomes, and base budgeting. (For more information on each approach, check out this post.) Any of these approaches can link to your strategic plan; however, base budgeting, still the most common form of budgeting in local government, may be the hardest to align with strategy because previously funded items continue to get funded. This makes it hard to drive change. Priority-based budgeting is the ideal if you want to make sure all funding dollars are working toward strategic goals.
3. Finalize the proposed budget and send it to the legislative body
After getting input from the department directors, the chief financial officer drafts a proposed budget, and reviews and negotiates it with department heads. Once this draft is complete, it is sent to the legislative body (e.g. city council, county council, or county board) for review.
Phase 2: Approval (Takes 1–2 months)
4. The legislative body reviews the budget in detail
Depending on the size of the legislative group, committees may oversee various parts of the budget. Each committee member reviews the budget in detail and makes revision suggestions as needed.
5. The legislative body may host a public budget hearing and information session for public input
Local government organizations exist to serve the public, so public input on the budget matters. Besides a public budget hearing and information session, they may gather input through citizen academies, discussion sessions, and surveys. Weigh public opinion alongside objective data (like demographic information, for instance), expert knowledge (like that of engineers), and your strategic goals and priorities.
6. The legislative body approves the budget
After community input and review, the legislative body approves and adopts the budget.
Phase 3: Implementation & Evaluation
Takes place throughout the fiscal year for which the budget was created.
7. The budget office monitors expenditures
Once you create your budget and tie it to your priorities or outcomes, you still have to manage that budget (and your strategy along the way). Throughout the year, monitor projected vs. actual spending and how departmental plans are progressing over time.
To do this, we recommend creating performance measures to help you determine if you’re accomplishing your strategic goals, clearly tying budget to performance. (Read more here about how one city department was able to validate its budget through performance management.) Data collection helps departments make budget decisions more effectively and holds everyone accountable for their actions. Remember to take the following steps:
- Assign an owner to every measure.
- Produce regular performance reports.
- Hold regular monthly, quarterly, and annual meetings to keep everyone on track.
- Periodically review your strategic plan to be sure the right goals are in place and the projects and measures continue to align with them.
8. At the end of year, the legislative body conducts a final budget reconciliation
This end-of-year reconciliation will reveal important information about how you actually used funds in relation to forecasted projections. (Note that some organizations do budget reconciliations on a quarterly basis to help guide spending, especially for departments that are spending ahead of their budgets. This allows them to bring their spending back inline before the end of the fiscal year.) You also want to ensure your records are accurate and complete.
This is also a good time to assess the performance of each department.
9. An independent auditor reviews the Annual Comprehensive Financial Report (ACFR)
Finally, an independent auditor reviews the financial statements in the report and confirms they follow accepted accounting principles.
Fort Collins, CO: A Model for Budget-Strategy Linking
The city of Fort Collins, Colorado, is a good example of how to link budget to strategy. Here are the highlights of its process:
- It all starts with the City's strategic plan, which considers input from residents, city council, and department heads. Every two years, the City takes the inputs it receives and creates a list of priorities within each of its seven strategic outcomes.
- Once the City Council formally adopts the City's proposed strategic plan, it kicks off the Budgeting for Outcomes process. Everything that is funded in the budget must link back to the strategic plan, so initiatives that will help the City achieve its strategic objectives receive funding.
- At the end of year one of every two-year budget cycle, the City has the option to adjust the year two budget up or down as needed to balance the budget for the second half of the cycle.
- The city regularly checks in on the progress of its strategic plan, not only to assess the performance of linked metrics around its goals, but also the progress of linked programs and services funded in the budget. The City uses ClearPoint Strategy so it can easily see the linkages between funded initiatives and strategic objectives, as well as linked performance metrics.
- The City periodically hosts a City Council retreat to discuss issues facing the municipality and how it may allocate resources in the next budgeting cycle. This information is passed along to the steering committee. Then, at the beginning of the budgeting year, the steering committee presents the strategic plan to the council, who approves the plan so the city can budget accordingly.
Fort Collins believed that linking budget to strategy would help it achieve its strategic objectives. That has paid off, and the City can better honor its commitments to the community.
Align Your Local Government Budget with ClearPoint Strategy Software
An effective local government budget does more than forecast revenue and expenses. It helps realize your community's vision and keeps leaders financially accountable. ClearPoint Strategy gives you the tools to run your budgeting process and keep it aligned with your strategic goals.
Improve your local government budget process. Book a demo with ClearPoint Strategy today and see how our software can simplify the steps from preparation to evaluation.
See how ClearPoint runs your government's strategic plan — book a demo
Common questions
Why should a local government budget be tied to strategy?
A local government budget should be tied to strategy because:
- Alignment with Goals: Ensures that financial resources are allocated in alignment with the strategic goals and priorities of the local government.
- Effective Resource Allocation: Helps in the efficient and effective allocation of resources to areas that will have the most significant impact on the community.
- Improved Accountability: Enhances transparency and accountability by linking budgetary decisions to strategic objectives.
- Performance Measurement: Facilitates the measurement of performance and outcomes against strategic targets.
- Long-Term Planning: Supports long-term financial planning and sustainability by ensuring that spending aligns with future strategic needs.
What are the two types of local government budgets?
The two types of local government budgets are:
- Operating Budget: Covers the day-to-day expenses of running the local government, such as salaries, utilities, and supplies.
- Capital Budget: Allocates funding for long-term investments in infrastructure, such as roads, schools, and public facilities. This budget focuses on projects that have long-term benefits and typically involve large expenditures.
How do local governments typically allocate funding in their budgets?
Local governments typically allocate funding in their budgets by:
- Assessing Needs: Identifying the needs of the community and prioritizing them based on strategic goals.
- Departmental Requests: Reviewing budget requests from various departments and agencies within the local government.
- Revenue Projections: Estimating available revenues from sources such as taxes, grants, and fees.
- Cost-Benefit Analysis: Conducting cost-benefit analyses to determine the most effective use of funds.
- Public Input: Incorporating feedback from public consultations and community meetings to ensure transparency and address community priorities.
What is the process for approving a local government budget?
The process for approving a local government budget typically involves:
- Preparation: Departments and agencies prepare their budget requests based on anticipated needs and strategic priorities.
- Review: The finance department reviews these requests and compiles a draft budget.
- Executive Proposal: The draft budget is presented to the local government’s executive body (e.g., mayor or city manager) for approval.
- Legislative Approval: The proposed budget is submitted to the local legislative body (e.g., city council) for review, discussion, and amendments.
- Public Hearings: Public hearings are held to gather input from citizens and stakeholders.
- Final Approval: The legislative body votes to adopt the final budget, which then becomes the official financial plan for the upcoming fiscal year.
What are some of the challenges of managing a local government budget?
Some of the challenges of managing a local government budget include:
- Revenue Uncertainty: Fluctuations in revenue sources, such as taxes and grants, can create uncertainty in budget planning.
- Competing Priorities: Balancing the diverse and sometimes competing needs and priorities of the community.
- Regulatory Constraints: Navigating complex regulations and compliance requirements that impact budget decisions.
- Resource Limitations: Managing limited financial resources while trying to meet the growing demands for public services and infrastructure.
- Stakeholder Engagement: Ensuring effective communication and engagement with stakeholders, including citizens, employees, and elected officials, to build consensus and support for budget decisions.